framework for our infrastructure that
allows distribution system operators
(DSOs) to anticipate power demand
and build-out new kilometres of
electricity grid through anticipatory
investments. At the same time, we
must make the best use of existing
grid capacity through digitalisation
and demand-side response mecha-
nisms. Smart charging is the lowest-
hanging fruit in this regard.
As detailed in our 2022 report,
smart charging can help manage grid
capacity by using algorithms to read
grid load and to shift EV charging
demand to times when clean and re-
newable generation is higher and
prices are cheaper. By optimising the
charging process, smart chargers can
reduce charging time, improve bat-
tery life, and minimise energy costs.
Being completely automated, the
charging process only requires the
driver to input the desired departure
time. The system then adjusts to
price signals, grid capacity and the
battery’s charge.
A McKinsey study on EV integra-
tion in Germany concludes that when
local EV penetration hits 25 per cent,
peak load can grow by 30 per cent in
the absence of smart charging. Using
a V1G (unidirectional charging)
strategy and time-of-use tariffs, the
peak load increase can be reduced by
16 per cent. Across different charging
segments, smart charging indicates
savings of 7-21 per cent peak load.
For these benets to be fully un-
leashed, however, increased aware-
ness and greater incentives to encour-
age EV drivers to smart charge
wherever possible at off-peak hours
and overnight are required.
Taking smart charging one step
further is the vehicle-to-grid (V2G)
technology. This charging solution
allows the bidirectional transfer of
electricity from the grid to the vehi-
cle’s battery for storage at times of
high generation, and back to the grid
when demand exceeds supply. With
V2G, EV drivers can move from
being a passive customer to an ac-
tive prosumer, who gets compensat-
ed for providing not only exibility,
but also the energy, previously
stored, back to the grid.
For these technologies to work,
however, data must be openly shared
across the entire e-mobility ecosys-
tem. Distribution system operators
F
ive years ago, the offer of elec-
tric vehicles (EVs) for the mass
market was still quite limited.
Today, car exhibitions are ooded
with new EV models, faster chargers
and longer-lasting batteries of differ-
ent ranges and costs. Pulling out of
exhibition venues onto the roads, EV
sales have scored records year after
year around the globe. Battery pro-
duction is getting cheaper and the
charging infrastructure is starting to
pick up the pace. But that’s not the
full picture.
Globally sales are on the rise but
rising more slowly in Europe and the
US. So far, demand has been propped
up by corporate eets rather than in-
dividuals. Yet, as this market satu-
rates, it will be harder to convince
individuals to keep up the pace.
China is leading the race with an EV
adoption rate of over 27 per cent –
Eurelectric and EY’s e-mobility re-
port last year showed – and the US is
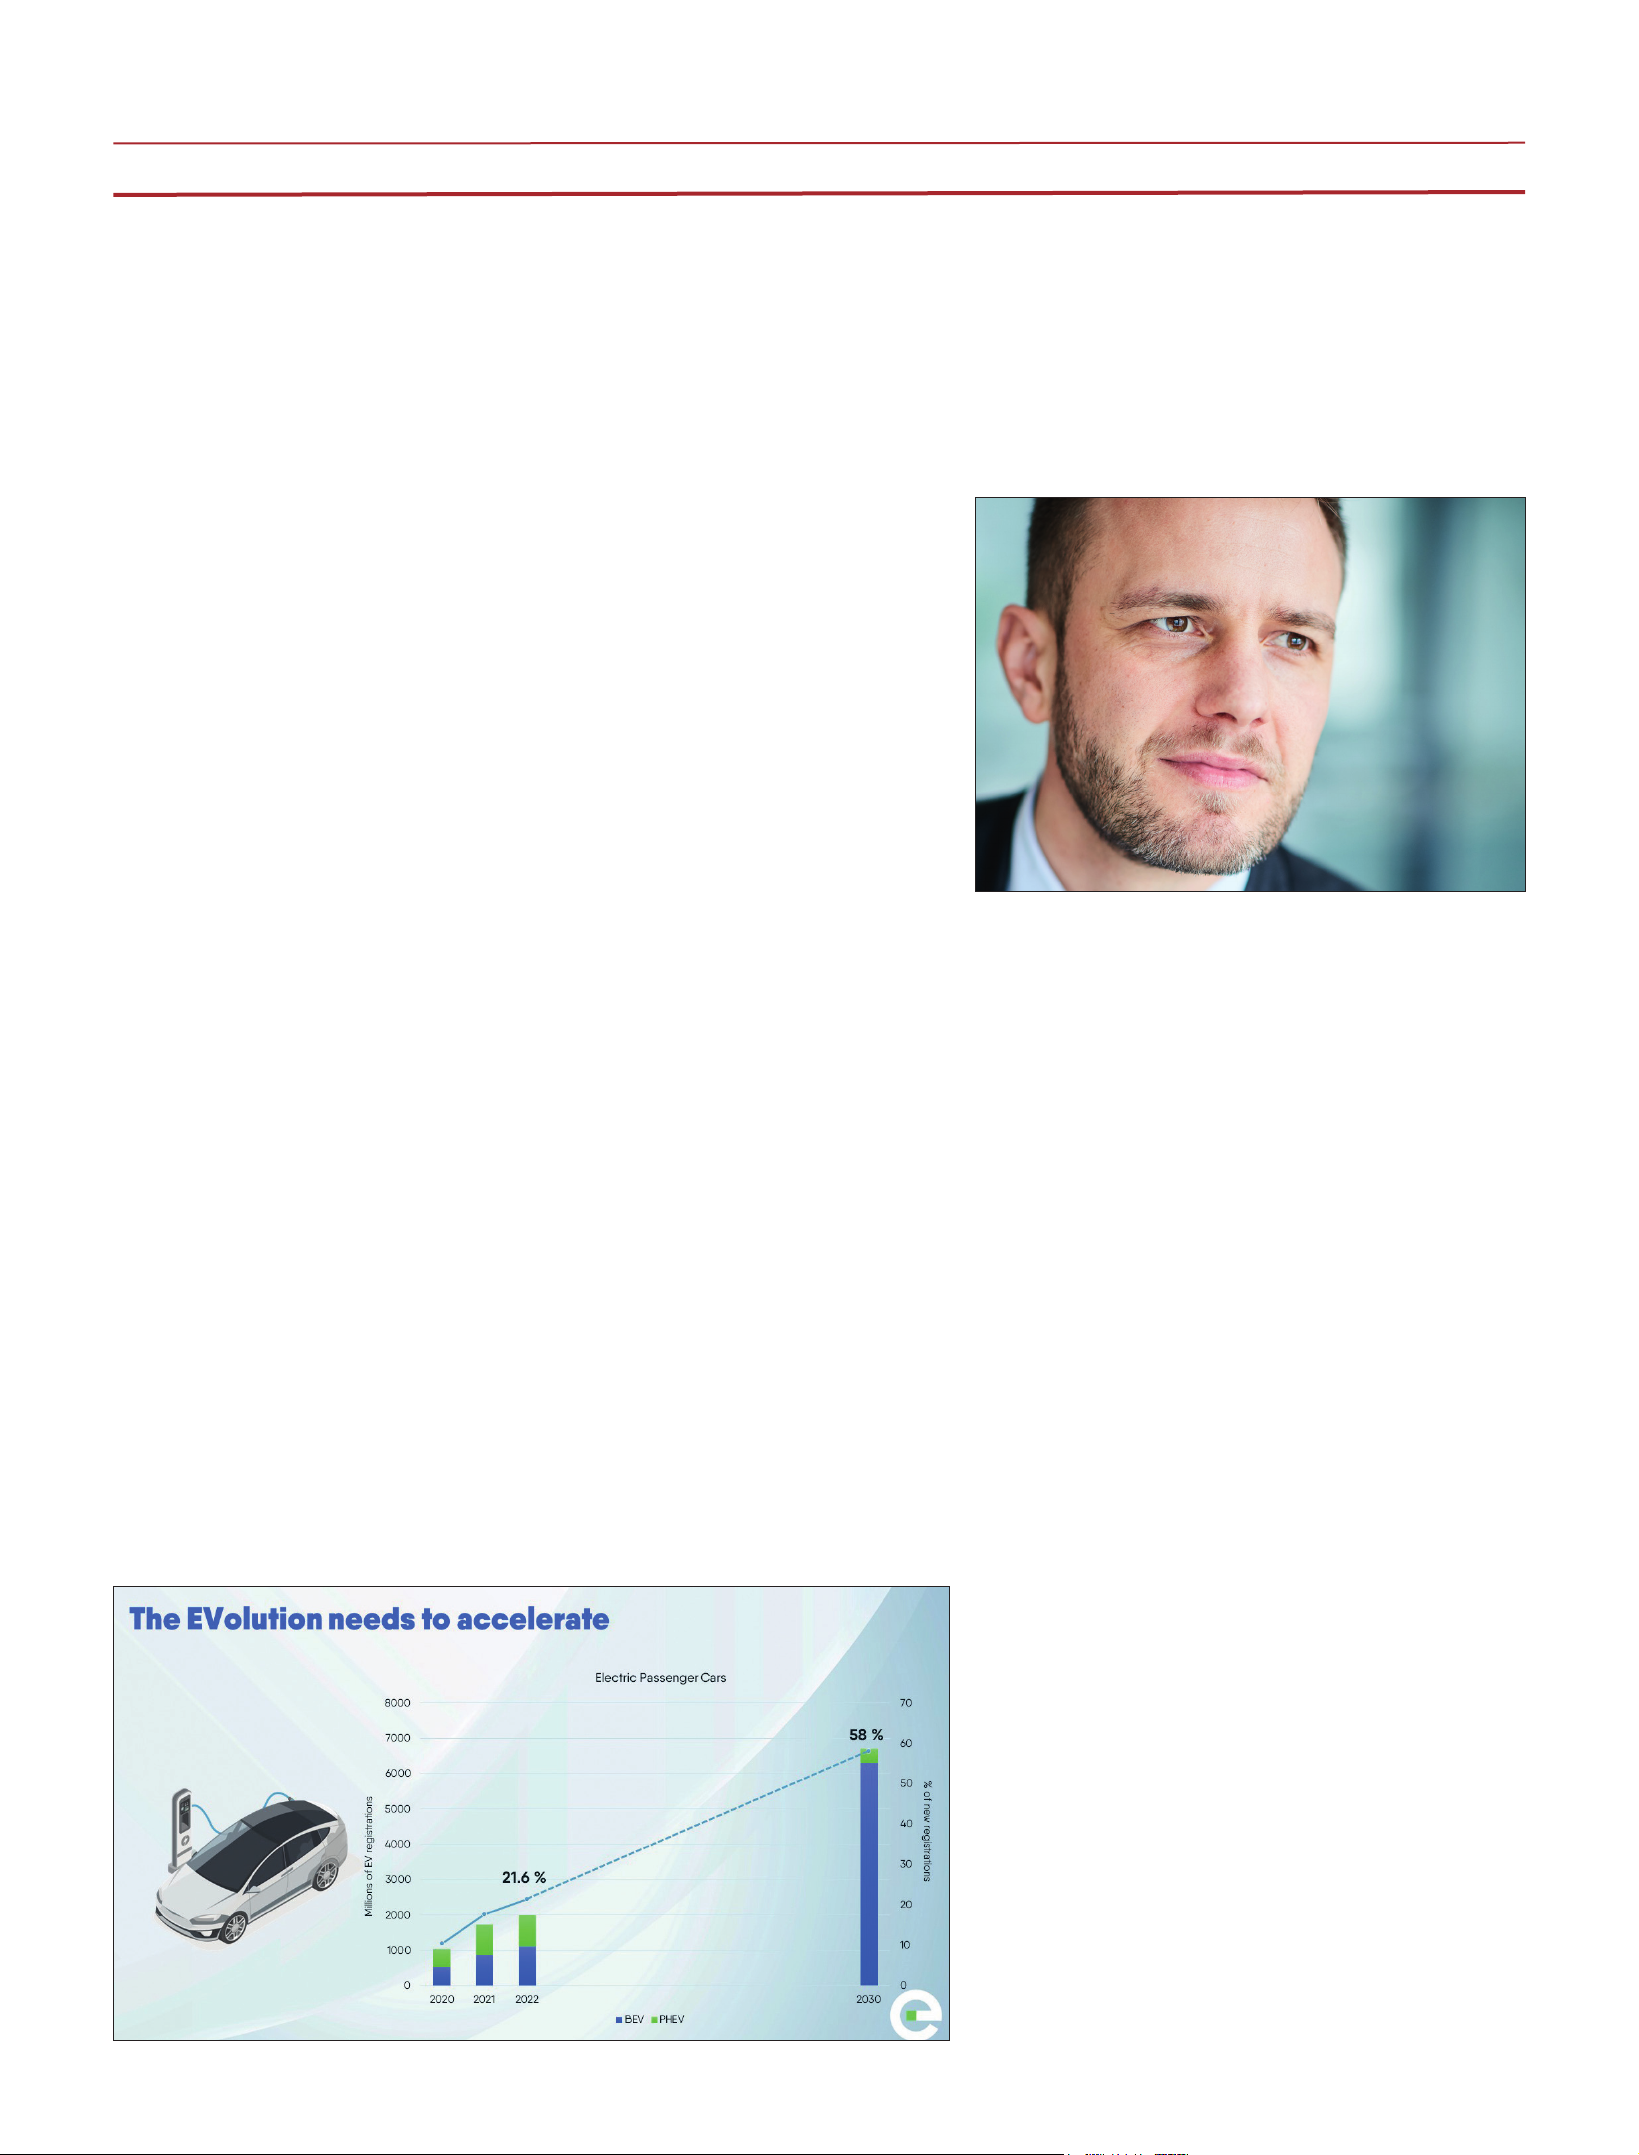
catching up. Europe has seen two
consecutive years of strong growth,
reaching 17 per cent in 2021 and just
over 20 per cent in 2022, but this must
reach 58 per cent in only 6.5 years to
meet the 2030 decarbonisation targets
– shows our latest ‘Power Barometer’.
Electric cars have reached an inec-
tion point. After rapidly making their
way into the transport sectors thanks
to early adopters and government
subsidies, EVs now need to appeal to
the mass market, but are the condi-
tions right?
They can be if we take an ecosys-
tem approach that puts the consumer
at the centre, strengthens collabora-
tion among all e-mobility actors
while benetting from the right pol-
icy incentives.
In Europe, however, the road to
mass-market adoption is getting
bumpy amid mixed political signals,
strong foreign competition and split
consumer sentiment.
A recent study from Transport and
Environment signals that high up-
front costs are still hampering a large
section of Europe’s population from
making the switch, as Western car-
makers tend to favour large and more
expensive luxury models for EVs.
Our latest study further adds that
consumer sentiment is split between
early adopters, reluctant buyers and
those mass-market consumers who
would like to purchase an electric
vehicle but choose not to due to the
scarce availability of charging sta-
tions, range anxiety and high upfront
costs. Yet it is precisely these mass-
market customers that EVs must
reach if adoption is to accelerate. For
this to happen, we must take an
ecosystem approach.
The e-mobility world is an entirely
different system from the one that
supports internal combustion engine
(ICE) vehicles. It is an ecosystem that
depends on widespread collaboration
among multiple actors enabled by
advanced digitalisation. These in-
clude original equipment manufac-
turers (OEMs) designing new EV
models with different battery ranges;
power system operators developing
and maintaining a resilient digitalised
grid to allow timely customer connec-
tions to charging infrastructure;
charging point operators (CPO) plan-
ning new and smarter charging infra-
structure where it is most needed; and
e-mobility service providers making
sure users have the best charging ex-
perience possible across Europe.
The ability to scale highly depends
on every player of this ecosystem
seamlessly working together. Other-
wise, we risk ending up in a situation
where the EV uptake will accelerate
faster than the ecosystem that can
sustain it. The key to resolving this is
a smart and grid-friendly charging
infrastructure.
By 2030 there will be around 70
million EVs on Europe’s roads and
2.8 million public charge points di-
rectly connecting to distribution
grids. If these chargers are not
smartly managed and strategically
planned to t the needs of the power
network, unpredictable uctuations
in demand coming from unknown
numbers of EV drivers charging si-
multaneously could lead to voltage
deviations and power losses. Up-
stream, the impact may translate into
increased energy prices.
To avoid this outcome, two things
must happen simultaneously. First,
Europe’s grid infrastructure must be
expanded to add new capacity and
accommodate future connection re-
quests. This can be achieved by
adopting a forward-looking planning
(DSOs) will need to track real-time
behaviour, from the vehicle to the
grid and back again. It will enable
utility companies to provide infor-
mation to the market on the state of
the grid so that the connected ecosys-
tem can, in turn, steer usage and
guarantee reliability for users. And,
in doing so, they can transform the
inux of EVs from a grid liability to
a grid asset.
CPOs can in turn make better use of
grid data and heat maps to strategi-
cally plan their charging infrastructure
build-out and anticipate connection
times based on the network status.
Yet, today, data is kept in silos, con-
sidered as a valuable currency to
preserve competitive advantage.
Making sure this data is interoperable
across the entire value chain should
be a clear focus for policymakers as it
is for our upcoming report, to be re-
leased in the coming days at EVision
2024 (March 6-7) in Brussels.
Reaching mass-markets also largely
depends on how well Europe is able
to engage with corporates. Commer-
cial cars and vans make up 20 per cent
of the total EU vehicle park but are
responsible for half of all road trans-
port emissions. Their electrication
must therefore be a matter of priority
to decarbonise transport rapidly as
well as making EVs more affordable.
Since corporate eets are usually up-
dated every three to ve years, electri-
fying them can contribute to a more
affordable second-hand EVs market
for the wider public.
Policymakers can once again make
the difference by setting ambitious
binding targets for the purchase of
zero-emission corporate cars and
vans by 2030 through the ongoing
Greening Corporate Fleet Initiative
and by extending the scope of the
initiative to heavy-duty vehicles.
Transforming road transport across
the entire continent will of course
come with challenges, but with the
right policy incentives, interconnect-
ed vision and commitment, Europe
can meet its ambition for transport
decarbonisation, energy security and
industrial competitiveness. The elec-
tricity industry stands ready to sup-
port the drive.
Kristian Ruby is Secretary General at
Eurelectric, the federation represent-
ing the European electricity industry.
THE ENERGY INDUSTRY TIMES - MARCH 2024
Industry Perspective
12
The e-mobility world
is an entirely different
system from the one
that supports ICE
vehicles. It requires
an ecosystem
that depends
on widespread
and seamless
collaboration between
multiple actors,
enabled by advanced
digitalisation. The key
to this is a smart and
grid-friendly charging
infrastructure
Kristian Ruby.
An ecosystem approach to
mass-market e-mobility
Europe has seen two
consecutive years of
strong growth but this must
reach 58 per cent in only
6.5 years to meet the 2030
decarbonisation targets
Ruby: Eurelectric is ready to support the EV drive
